November has a particular quality to it in financial terms. The year is close enough to its end that patterns have become clear, but there is still enough time remaining to do something about them before December closes the door. It is not a moment for grand resolutions or dramatic overhauls. It is a practical window to sit down, look honestly at where things stand, and decide whether anything is worth addressing before the new year arrives.
This does not need to take long. A focused two hours with the right information in front of you tends to reveal more than months of vague intention.
What this kind of review is actually for
A year-end financial review is not the same as a full financial plan. It is closer to a sense-check: a deliberate pause to ask whether the year went broadly as intended, where it did not, and whether any of the gaps are worth acting on now rather than carrying into the next year.
The value is not in achieving perfection. It is in moving from a passive relationship with your finances, where things happen by default, to an active one, where you are making conscious decisions even if those decisions are sometimes to leave things as they are.
Income and spending
The most straightforward place to start is with what came in and what went out. Most people have a rough sense of this but a less accurate one than they think.
Pull up three or four months of bank statements and look at the pattern rather than the individual transactions. Has spending in any category drifted significantly from where you intended it to be at the start of the year? Are there subscriptions or recurring costs that have quietly accumulated without much thought? Has income changed in a way that has not yet prompted a corresponding adjustment to saving or spending habits?
The point is not to account for every pound. It is to identify whether the overall shape of the year reflects your intentions or whether things have drifted.
Savings and whether the year moved them forward
If you set out with any savings goals at the start of the year, November is a reasonable moment to assess how they have progressed. Not with a view to criticising what has or has not been achieved, but with a practical eye on whether anything in the final weeks of the year is worth adjusting.
If savings have grown roughly as intended, the review might simply confirm that and prompt a decision about what to aim for next year. If savings have fallen short, it is worth understanding why. A one-off cost in an otherwise consistent year is different from a structural gap between income and savings ambition that will persist unless something changes.
For anyone who holds savings in accounts that have not been reviewed for some time, it is also
worth checking whether the interest rate is still competitive. Rates change, and money sitting in an account that was opened years ago may be earning considerably less than alternatives currently available.
Debt
If any debt has accumulated during the year, the end of the year is a useful moment to look at it clearly. Not with anxiety, but with the same practical intent as everything else in the review.
What does the total picture look like? Is debt reducing, static, or growing? Are there any interest rates attached to existing debt that are worth revisiting? Are there any introductory rates due to expire that will result in a higher cost if not addressed?
For anyone who has been managing debt throughout the year, a brief review of whether the approach is working tends to be more useful than simply continuing on autopilot.
Protection and insurance renewals
The end of the year often brings a cluster of insurance renewals, and it is easy to accept them without much thought at a busy time. November is a reasonable moment to check which renewals are due in the coming weeks and whether any of them warrant comparison against alternatives before accepting the renewal price. There are a wide range of comparison websites you can visit to compare the alternative policies available and to obtain a more competitive premium.
For protection insurance such as life cover or income protection, a renewal is also a prompt to consider whether the level of cover still reflects current circumstances. A year in which income has changed, a family has grown, or a mortgage has shifted is a year in which protection needs may have changed too.
Pensions and tax-efficient saving
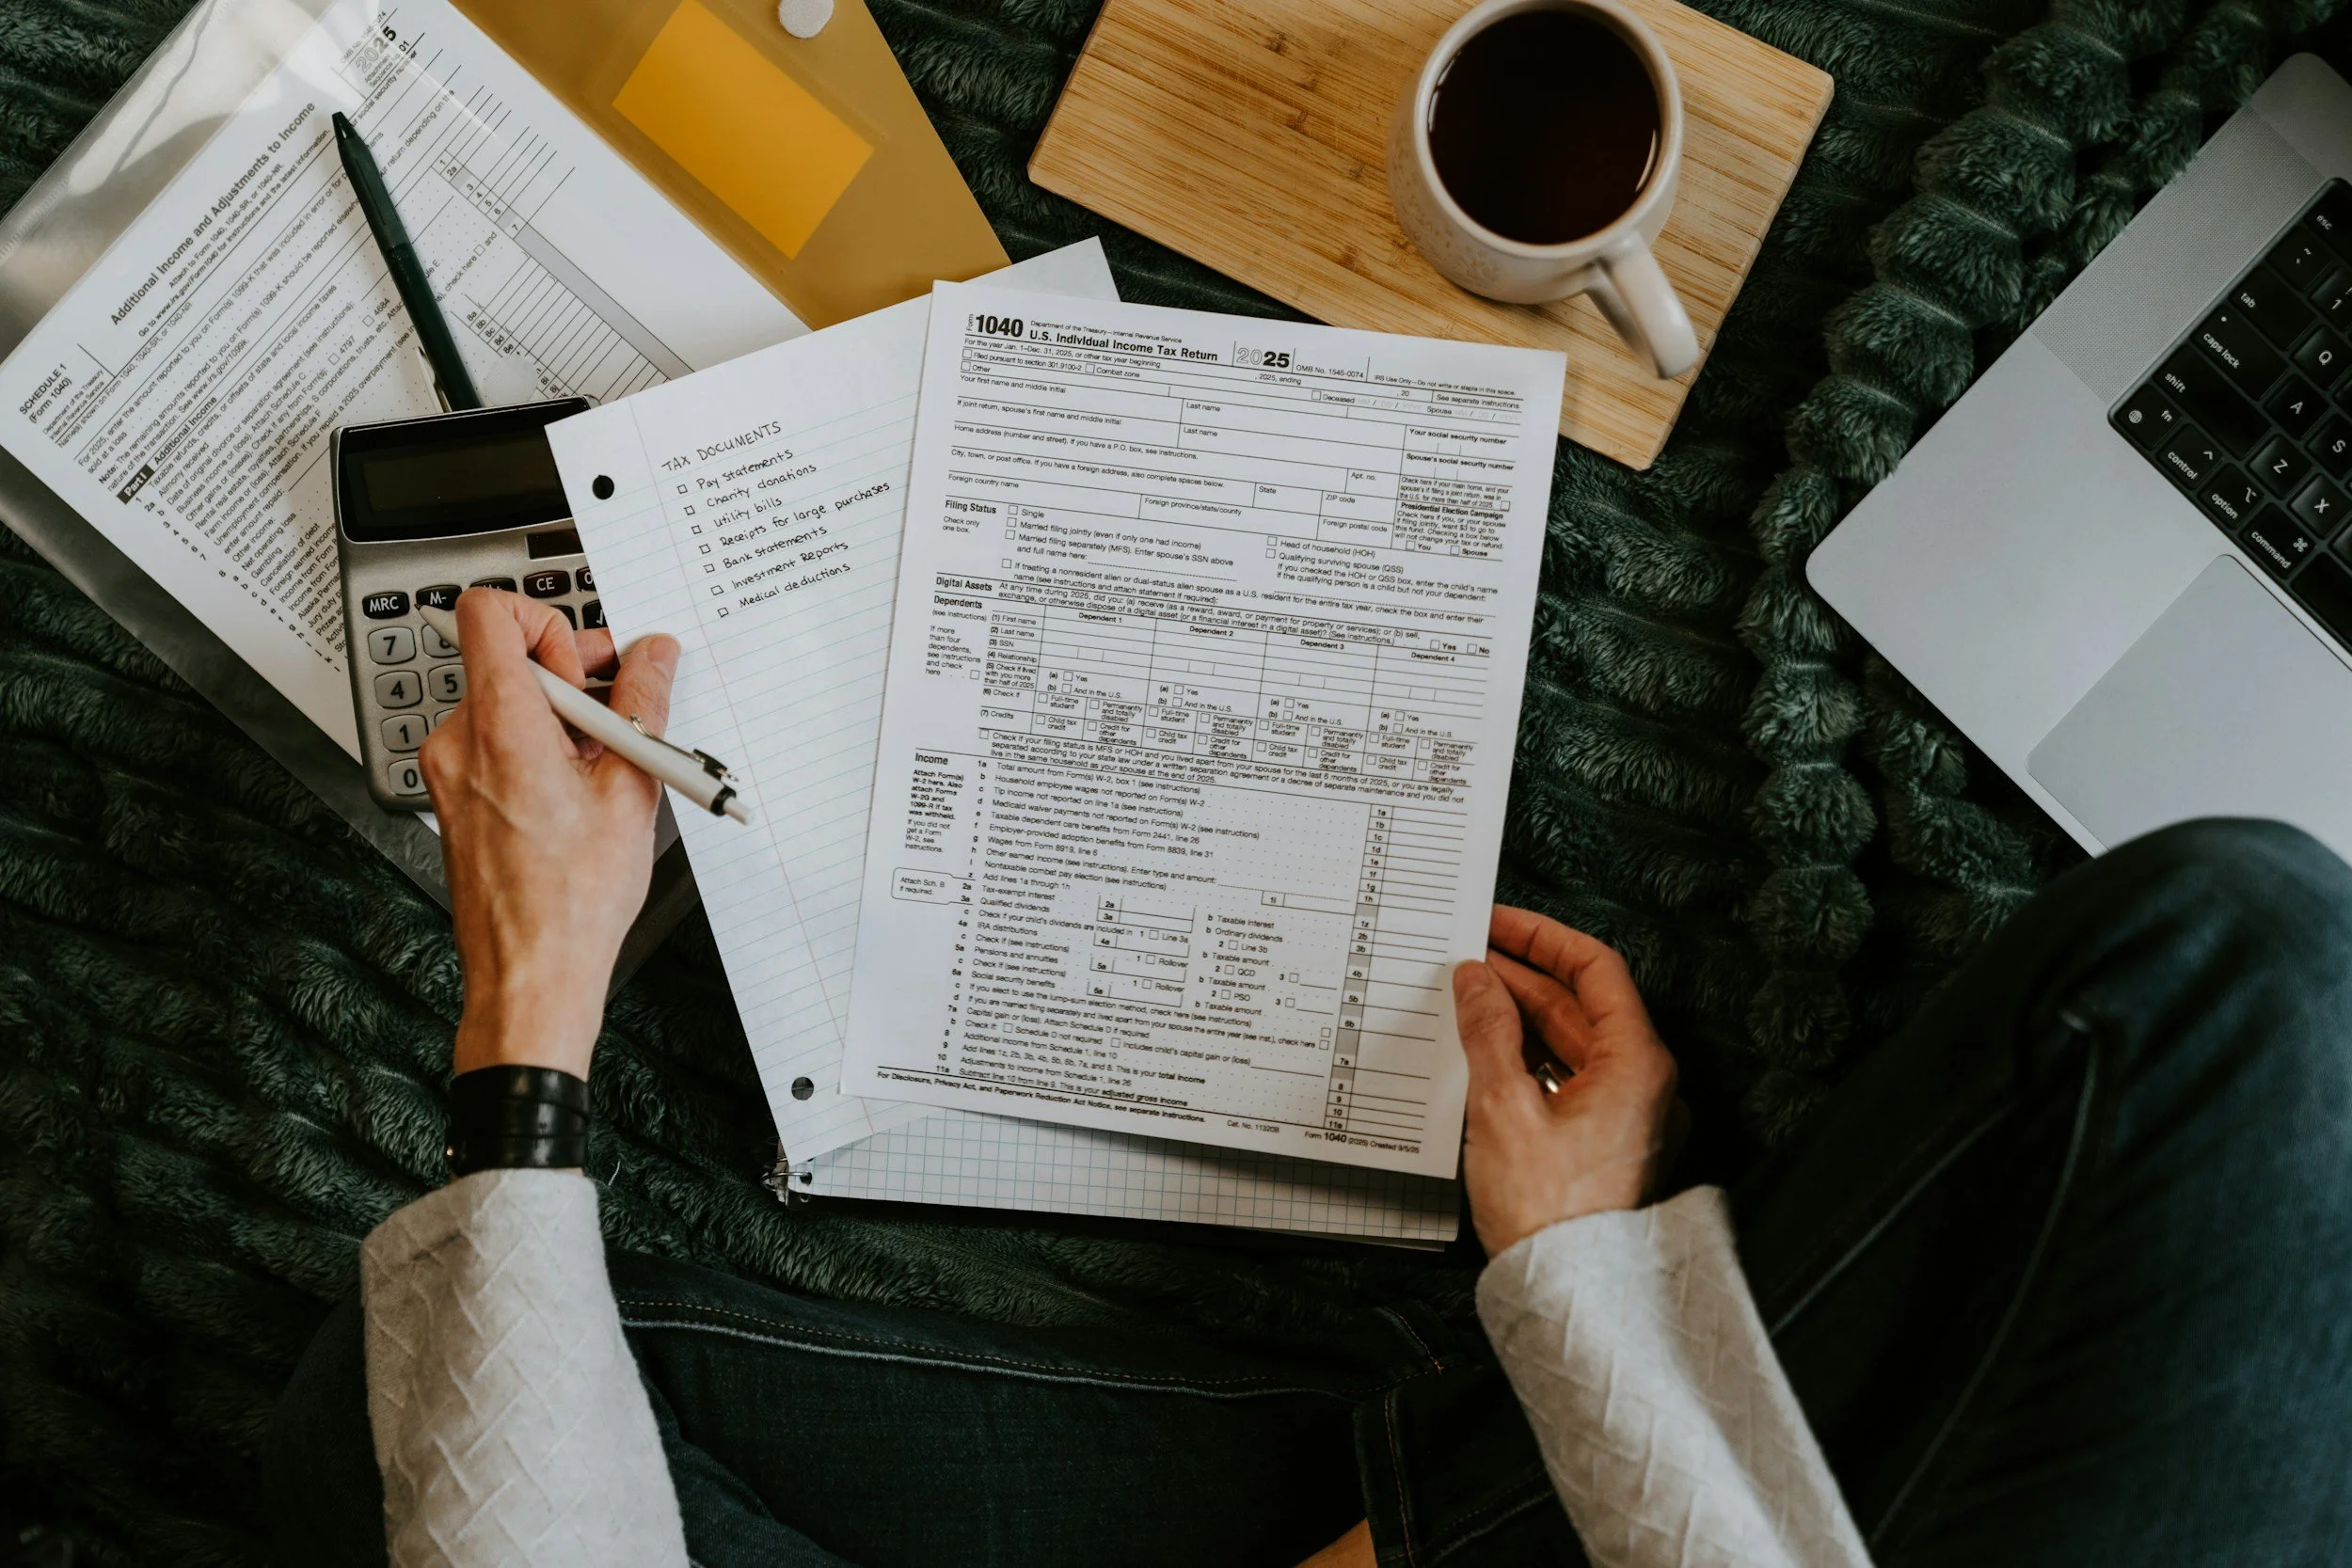
The tax year ends in April rather than December, so there is no immediate deadline pressure on ISA or pension contributions at this point in the calendar. However, November is a reasonable moment to check where you stand against any contribution intentions you had for the year, and whether there is scope to make further use of available allowances before April.
For anyone who is self-employed or who has variable income, the end of the calendar year can also be a prompt to review whether pension contributions for the year are tracking as intended.
Pension values can go down as well as up, and the tax rules around pensions and ISAs reflect the position as at 2026 and are subject to change.
What to carry into the new year
Once you have worked through the areas above, the most useful output from a year-end review is a small number of clear intentions for the year ahead rather than a long list of aspirations. Two or three things that are genuinely worth doing differently tend to be more actionable than
ten.
Those intentions do not need to be decided in the review itself. The review is for getting the picture clear. The decisions can follow.
Frequently asked questions
Is November too early for a year-end financial review?
No. November is arguably the better time to do it compared with late December, precisely because there is still time to act on anything that comes up before the year ends. A review in the last week of December is more of an audit than a review, as there is little scope to change anything. November gives a few weeks of runway.
What if I find the picture is worse than I expected?
That is exactly the kind of thing a review is designed to surface. Finding out in November that savings have not progressed as planned, or that debt has grown more than intended, is more useful than discovering the same thing in February with another year already underway. The information itself is not a problem. It is the starting point for deciding what to do differently.
Should I include my pension in a year-end review?
A basic check is worthwhile, particularly around whether contributions are tracking as intended and whether there are any older pension pots you have lost track of during the year. A more thorough pension review tends to benefit from professional input, particularly if your circumstances have changed significantly during the year.
Do I need an adviser to do a year-end financial review?
Not necessarily for the review itself, which is largely a personal sense-check. However, if the review surfaces questions that feel genuinely complex, or if it reveals a significant gap between where things are and where you would like them to be, a conversation with a qualified financial adviser tends to provide a more complete picture of what options are available.
A final note
A year-end financial review is one of the more practical habits in personal finance, and one of the easiest to skip in a busy November. The return on a couple of focused hours tends to be disproportionate to the effort involved, not because it will reveal dramatic surprises, but because it replaces vague anxiety with a clear picture. And a clear picture, even an imperfect one, is almost always a better starting point than the alternative.